
The UAE’s Base Rate is now 3.9% after the Central Bank raised it by 25 basis points from 3.65%, effective September 17.
If you have a mortgage, personal loan or credit card, that does not mean your rate automatically jumped by exactly 0.25 percentage points overnight.
The CBUAE Base Rate increased by 25 basis points to 3.9%, changing the UAE rate environment for borrowers, businesses and savers.
UAE mortgage holders, borrowers, SMEs, prospective homebuyers and savers comparing deposit returns.
Borrowers can review reset dates and refinancing economics, while savers can compare deposit yields with other low-risk options as rates adjust.
A 25-basis-point Base Rate increase does not mean every mortgage, loan, card or deposit reprices by exactly 0.25% or on the same date.
Banks and money-market benchmarks may adjust through their normal pricing cycles; borrowers with variable products will feel changes according to contract reset terms.
Check whether your loan is fixed or variable, identify its benchmark and margin, and find the next reset date before assuming your payment has changed.
Savers may see stronger deposit offers, while the effect on borrowers depends on whether their credit is fixed, variable or benchmark-linked.
This is a monetary-policy change rather than a programme; its effect reaches customers through individual bank products and contracts.
Watch EIBOR, bank mortgage offers, deposit rates and the September 22 profit-rate announcement for the new five-year Retail T-Sukuk.
The Central Bank decision changes the monetary-policy benchmark. What happens to your own payment depends on the product, your contract, whether the rate is fixed or variable and when the bank reviews it.
What the Central Bank Actually Changed
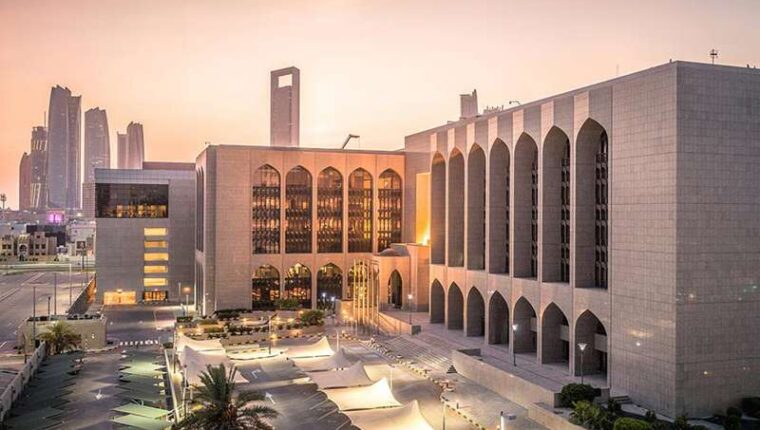
The Central Bank of the UAE raised the Base Rate applying to its Overnight Deposit Facility by 25 basis points, from 3.65% to 3.9%. The change took effect on Thursday, September 17.
The CBUAE kept the rate for borrowing short-term liquidity through its standing credit facilities at 50 basis points above the Base Rate.
The move followed the US Federal Reserve’s 25-basis-point increase. That connection is structural rather than surprising: the UAE dirham is pegged to the US dollar, and the CBUAE Base Rate is anchored to the Federal Reserve’s Interest Rate on Reserve Balances.
A Base Rate Is Not Your Mortgage Rate
The Base Rate signals the general stance of monetary policy and provides a floor for overnight money-market rates. Retail banks still price individual mortgages and loans under their own product terms.
If your mortgage is fixed for a defined period, the agreed rate generally remains fixed during that period. If it is variable or linked to a benchmark such as EIBOR, the cost can change when the contract reaches its next reset or review point.
So the useful question is not simply, “Did the CBUAE raise rates?” It is: what benchmark is my loan linked to, what margin does my bank add, and when is my next reset?
New Borrowing Can Feel It Differently
A higher policy-rate environment can feed into the price banks offer for new mortgages, business loans and other credit. It can also affect floating-rate borrowing already in place.
But a 25-basis-point Base Rate move is not a promise that every bank adds exactly 25 basis points to every retail product. Customer risk, loan-to-value, term, salary transfer, bank margins and promotional pricing can all affect the final offer.
For SMEs, this lands on the same day as another important banking change Robius covered: the UAE’s new SME Customer Protection Regulation, including a three-business-day account-opening standard for qualifying low-risk applicants. Easier process does not necessarily mean cheaper credit.
Savers Are on the Other Side of the Rate Move
Higher rates are not only a borrower story. Banks may offer more attractive returns on some savings and fixed-deposit products when market rates are higher.
Again, there is no automatic pass-through. Each bank decides the rate it offers depositors, and promotional or tiered savings accounts can behave differently from fixed deposits.
The timing is also interesting because the UAE has just announced a new five-year Sovereign Retail T-Sukuk starting from AED1,000. Its profit rate is due to be announced on September 22, giving retail savers another yield to compare against bank deposits once that number is public.
What to Check on Your Own Loan
- Fixed or variable: find out whether your current rate can move.
- Benchmark: check whether the loan is linked to EIBOR or another reference rate.
- Margin: identify the bank’s margin added above the benchmark.
- Reset date: a benchmark can move before your payment does.
- Early settlement or switching costs: compare the full cost before refinancing purely because rates changed.
The Bottom Line
The CBUAE has tightened its Base Rate to 3.9%. That matters because it changes the rate environment across the UAE economy.
It does not rewrite every household loan contract at 12:01 a.m. The impact reaches residents through the terms of the actual mortgage, loan, card or deposit they hold.
Sources
- Central Bank of the UAE / WAM, 16 September 2026: Base Rate increase from 3.65% to 3.9%, effective September 17, and standing credit facility terms — reported via Sharjah24 / WAM.
- Gulf Business, 17 September 2026: UAE borrower and saver implications following the rate increase — Gulf Business.
Checked 17 September 2026. This article explains the policy-rate change and does not assume that any individual bank product reprices automatically. It is not financial advice.
Robius.news — Dubai, UAE — 2026 | Built to be first. Built to be trusted.