 UAE, UNFILTERED
J.P. Morgan Opened a New DIFC Private Bank Branch. It Was Not a First Arrival
J.P. Morgan Private Bank has opened a DFSA-regulated DIFC branch after tripling its Dubai private-banking team. The bank has been in DIFC for decades, so the real change…
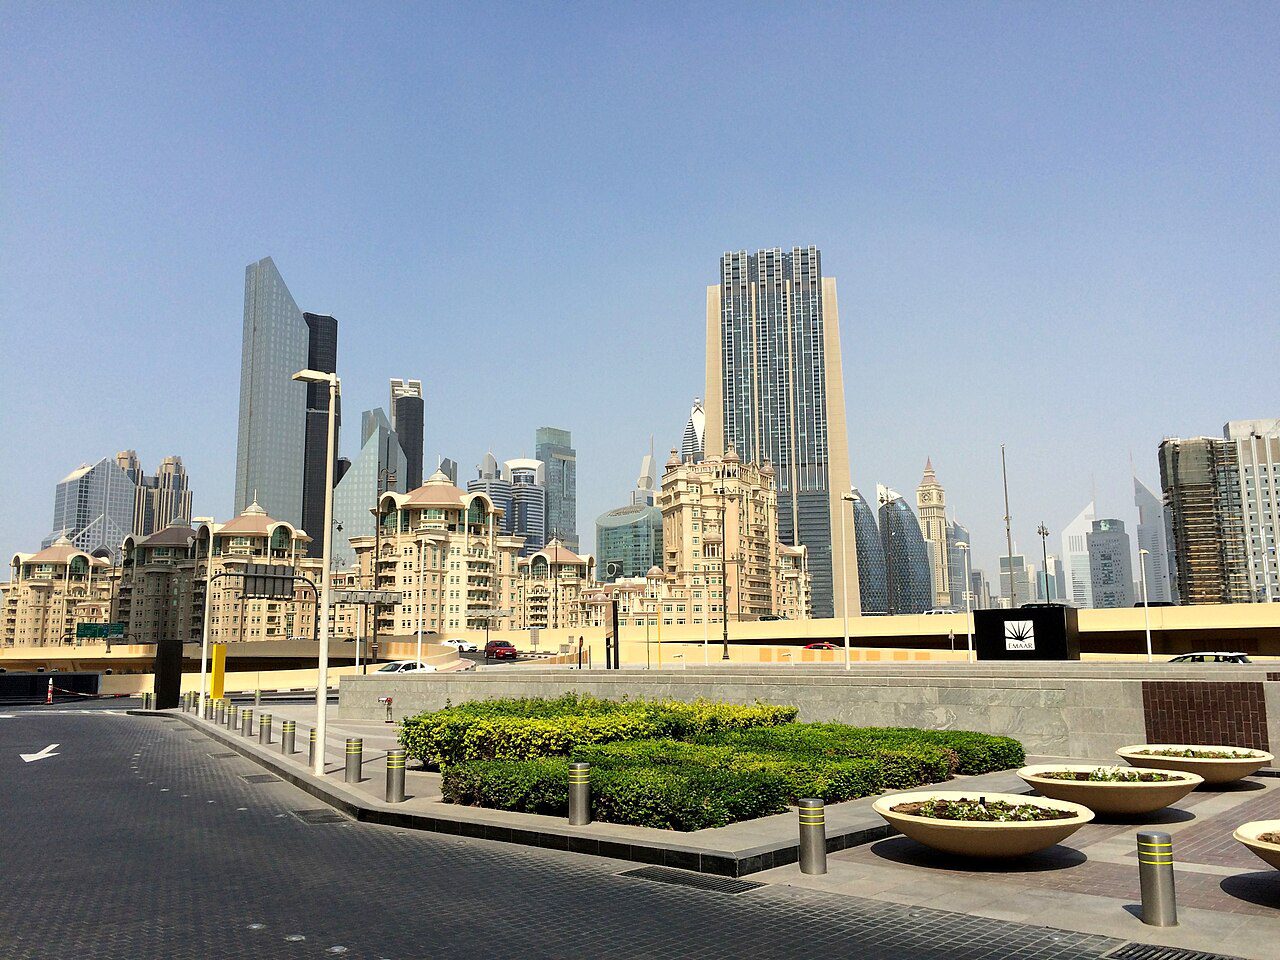
The opened branch deepens existing DIFC operations, creating a dedicated regional private-banking platform rather than a first group arrival.
UAE private wealth clients, family offices, banking professionals and financial-services providers.
The announcement omits absolute staff counts, universal minimum assets and precise terms; separate JPMorgan entities have distinct DFSA permissions.
Track client services, account contracts, applicable DFSA-authorised entities and announced staffing or asset milestones.
Before opening an account, verify the contracting entity, regulatory permissions, custody arrangements, fees and eligibility in writing.
J.P. Morgan Private Bank has opened a dedicated branch in Dubai International Financial Centre, but the American banking group is not arriving in Dubai for the first time. The real change is the addition of a dedicated private-banking platform to a financial-centre presence that already includes corporate banking and investment services.
In a 2 November 2026 statement, J.P. Morgan Private Bank and DIFC said the new branch is regulated by the Dubai Financial Services Authority and will serve clients in the UAE and, where permitted, the wider region.
The statement says the bank more than tripled the size of its Dubai-based private banking team in the preceding 12 months as it prepared for authorisation. It did not publish the starting or ending headcount, so it would be misleading to turn a threefold increase into a specific number of newly hired bankers.
What changed, and what already existed?
J.P. Morgan says its UAE relationships span more than five decades. It has also used DIFC as a regional base for corporate and investment banking for more than 20 years. The latest expansion adds a dedicated structure for private banking and local coverage of wealthy individuals and families.
| Activity | Publicly established status |
|---|---|
| J.P. Morgan corporate and investment banking in DIFC | Established presence for more than two decades |
| JPMorgan International Advisors (DIFC) Limited | Separately listed as a DFSA-authorised financial firm |
| J.P. Morgan Private Bank’s dedicated branch | New branch announced open on 2 November 2026 |
| More than tripled Dubai private banking headcount | Firm’s reported growth over 12 months; absolute numbers not supplied |
That distinction matters because financial groups often operate through multiple legal entities. A familiar global brand does not mean every investment, deposit, custody or credit product is provided by the same regulated firm under identical protections.
The regulatory question clients should actually ask
DIFC’s announcement identifies DFSA regulation. The DFSA’s public register contains an existing entry for JPMorgan Chase Bank, N.A., licensed in DIFC since September 2006, and another for JPMorgan International Advisors (DIFC) Limited, licensed in June 2026.
Those entries demonstrate the importance of checking the specific legal entity rather than treating the group name as a licence number. The cited press announcement does not itself specify which legal entity will be the contracting party for every service delivered through the new private banking branch. Robius therefore does not assign a single existing DFSA reference to every product offered by the new branch.
A prospective client should check their account-opening documents, the legal entity named in the agreement, the precise DFSA permissions that apply, and where assets or deposits will legally be held. An investment advisory service, an execution service and a banking deposit can have different regulatory and contractual arrangements.
A new private banking base is not a retail-bank launch
Private banking typically serves clients with substantial investable assets and more complex needs around portfolios, financing, international holdings and family wealth. The opening of a dedicated private-banking branch is not an announcement of a new mass-market current account, free debit card or app for all UAE residents.
The parties did not give a universal minimum asset threshold, fee schedule or list of products newly available to every customer in their press release. Those details may depend on client profile and the particular legal entity involved. It would be irresponsible to invent eligibility rules from a branch-opening headline.
The move nevertheless matters to Dubai’s competition for global wealth-management relationships. Wealthy families often need advisers who understand local structures and can coordinate with international investment, tax and estate-planning teams. Having people on the ground may improve continuity and access to expertise, but an office address alone does not guarantee lower costs or better portfolio returns.
Why staffing is a more concrete signal than a ribbon-cutting
The disclosed staffing expansion provides one tangible indicator of commitment. The bank said it had more than tripled its Dubai-based private-banking team over 12 months before receiving final authorisation. The firm identified Selim Elgen as UAE Market Head and Senior Executive Officer, with Karim Rekik leading the wider Middle East private-banking business.
Still, a relative growth figure needs a denominator. Tripling a team of 10 and tripling a team of 100 are very different undertakings. The announcement does not say which case is closer, so readers should not infer a specific hiring scale or the number of active clients served.
Independent reporting by The National frames the branch as part of intensified competition among international wealth managers. The business case is plausible, but the press release itself supplies no public client-asset target or revenue forecast for the new platform.
What does the branch change for the wider DIFC market?
At a financial-centre level, a large group’s decision to expand a dedicated wealth business adds senior staff, regulated capacity and potential demand for legal, compliance, reporting and professional services. But those are potential spillovers, not a measured contribution attributable to this branch.
It also reflects a different kind of international expansion from a fintech licence application. Robius recently examined Robinhood’s DIFC approval and still-planned UAE consumer app. The stages should not be confused. Robinhood’s planned rollout is not evidence of a live app; J.P. Morgan’s announcement specifically states that its new private-banking branch has opened.
That illustrates why precise verbs matter in financial journalism: applied, authorised, opened, offering and widely available describe different operational milestones.
What clients should verify before choosing any private bank
- Confirm the legal service provider and the relevant financial regulator through an official register.
- Ask whether the bank is providing advice, arranging investments, holding custody, extending credit or taking deposits, and which entity performs each role.
- Request written details of fees, product restrictions, conflicts of interest and any applicable minimum relationship size.
- Check how cross-border services, custody and dispute resolution work for the actual agreement, not the global brand in the advertising.
- Compare service quality and portfolio suitability rather than assuming the newest branch is automatically the best choice.
These are due-diligence questions, not allegations against J.P. Morgan. They apply equally to any global private bank operating through multiple jurisdictions and legal entities.
The Robius Read
J.P. Morgan’s new DIFC private-banking branch is a real operational addition, not simply another licence application. But the headline is not that a previously absent global bank has suddenly discovered Dubai. It has operated in the UAE for decades.
The meaningful story is the depth of its commitment to the wealth-management market, and whether that local platform eventually produces differentiated services for clients. For now, the verified milestones are the branch opening, DFSA-regulated status as described by the firm, and its self-reported expansion of the Dubai-based team.
Sources and reporting method
- DIFC / J.P. Morgan Private Bank: new branch announcement, 2 November 2026
- DFSA public register: JPMorgan Chase Bank, N.A. (DIFC Branch)
- DFSA public register: JPMorgan International Advisors (DIFC) Limited
- The National: private banking expansion context, 2 November 2026
Reporting method: Direct DIFC statements are distinguished from regulatory entries, and neither is assumed to identify every customer’s contracting entity. No asset minimum, account eligibility or headcount has been inferred beyond what the sources disclose. Checked 3 November 2026.