 UAE, UNFILTERED
Your UAE Credit Score Has Two Scales
Etihad Credit Bureau's new Score 3i uses different scales for established borrowers and newcomers. Robius explains the 36-month view, BNPL reporting, six-month recovery limits and what residents should…
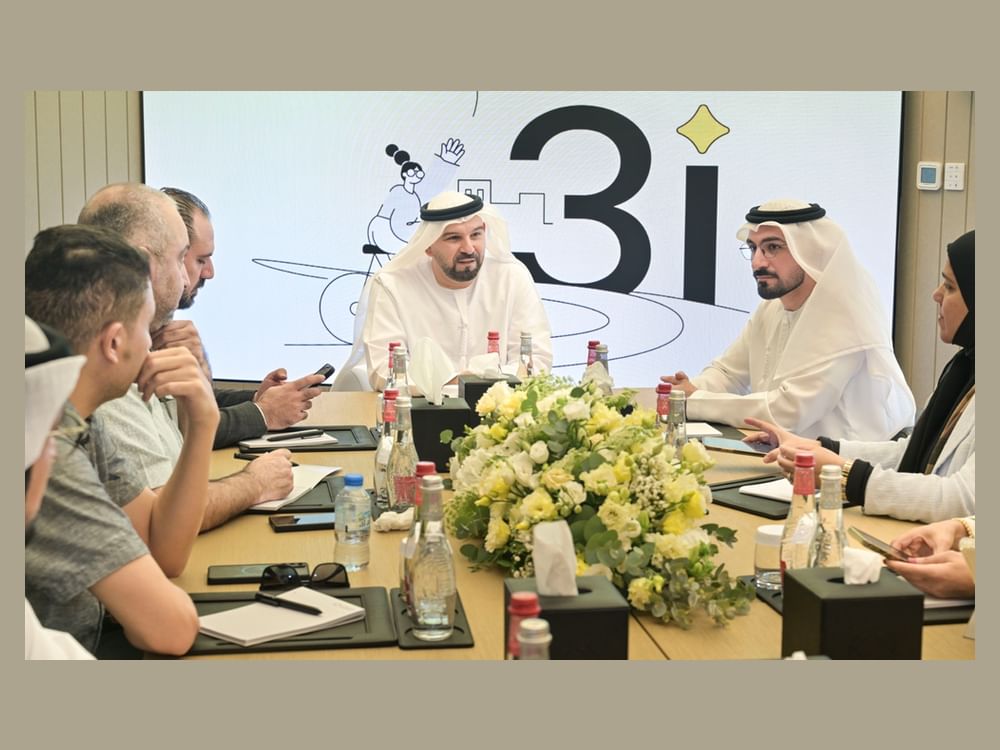
Credit Score 3i uses separate 300–850 and 300–650 ranges, a 36-month assessment and conditional faster recovery; an isolated number can mislead.
UAE residents, new arrivals, borrowers rebuilding credit, lenders, landlords, brokers and consumer finance advisers.
A six-month improvement is not guaranteed. BNPL report visibility does not prove a specific numeric score effect. Lenders retain their own approval criteria.
Watch how lenders use the two segments and whether the Bureau publishes updated grade bands and further BNPL scoring guidance.
Check your score's model label, inspect the full report, verify facilities and settlements, and request correction of inaccurate data through the Bureau.
A UAE resident with a credit score of 640 may now be near the top of one official scoring range, but much further from the top of another. Etihad Credit Bureau launched Credit Score 3i on 29 October 2026, with separate ranges for established borrowers and eligible people with limited credit histories. It also expanded the period of behaviour assessed from 24 to 36 months and introduced clearer explanations of score factors.
That changes how UAE residents should read the number before applying for a loan, card or rental. A score is not a loan approval, a six-month recovery window is not a promise, and the arrival of buy-now-pay-later data on a credit report does not automatically mean each instalment changes the numeric score. The useful first step is to identify which scoring model applies, inspect the underlying report and correct any inaccurate entries before a lender or landlord makes a decision.
One number, two different scales
The Bureau’s new model uses a range of 300 to 850 for individuals with established credit histories. Eligible newcomers to credit or to the UAE with limited histories can receive a separate score on a 300 to 650 scale. The difference is structural, not a 200-point penalty for arriving recently.
Consider two hypothetical residents who each see 640. For a person in the limited-history segment, 640 is close to that model’s published ceiling. For a mature-file borrower, 640 is considerably below the 850 ceiling. That does not mean one person is necessarily safer to lend to: the models address different available evidence, and the Bureau has not published a public conversion table making the numbers directly comparable.
The practical rule is to read the score together with its model label, the factors shown in the report and the date it was generated. A landlord, broker or bank that quotes a bare number without the model context may create an unfair comparison. A newcomer should not assume that a 650 ceiling means they are barred from higher-quality credit products; eligibility still depends on the lender’s own assessment.
The change also makes old screenshots and score advice unreliable. Older Robius coverage of the Bureau’s refreshed credit-report app described the former 300-to-900 scale. That historical figure must not be used to interpret a new personal Score 3i result.
Three years of behaviour, not three years of punishment
Credit Score 3i assesses up to 36 months of credit behaviour, compared with 24 months under the previous model. The Bureau says the longer view captures patterns in how financial obligations are managed rather than relying only on a narrower recent period. This is a change in model assessment, not a new law requiring residents to wait three years before borrowing.
The full individual Credit Report already provides a three-year history of loans, credit facilities and bills, alongside personal information, last reported salary, an income-utilisation measure and court-ordered financial obligations. A longer model window and the report’s history should not be treated as interchangeable: one describes the score’s methodology, the other describes the data a reader can inspect.
A single good month may be useful, but a pattern of timely repayment is stronger evidence. Equally, an old late payment may still be visible even after the balance is cleared. Readers should separate three questions: Is the entry factually correct? Is the debt now settled? And how is the model interpreting the wider record? Settling an obligation and correcting an erroneous record are different actions.
The six-month recovery headline has a condition
One of the launch’s most attractive claims is that improved behaviour following a settled default may be reflected in the score within six months. The Bureau explicitly says an increase is not guaranteed. Subsequent payments, the overall profile, new adverse information and the model’s criteria all matter.
For someone rebuilding after missed instalments, this is an opportunity for a faster reassessment, not an automatic reset. It does not erase accurate historical information or oblige a lender to approve a mortgage after six months. A person whose default is settled but whose other obligations remain overdue may see a different outcome from someone who consistently meets every payment.
A useful recovery log has three parts: evidence that the original default was settled, a month-by-month record of later payments and a dated copy of the Bureau report. Compare changes in the underlying facts, not just movement in the headline score. Be cautious of paid services promising a fixed increase or a guaranteed deletion of accurate records.
BNPL is a reporting change, not a shortcut to a better score
The Bureau’s October announcement says its credit-reporting coverage expanded in 2026 to include buy-now-pay-later accounts and other short-term credit products. This matters because a small instalment plan may be visible to an institution assessing the applicant’s total commitments. The October release does not say that every BNPL entry directly raises or lowers the numeric Score 3i.
Those are different stages: a provider reports an account, the Bureau assembles the credit file, a scoring model produces an indicator, and an individual lender makes its own decision. A bank may consider obligations visible in the report even when a particular data category is not part of the model’s numeric calculation. Consumers should not use BNPL specifically as a guaranteed score-building technique.
This distinction also requires care when reading Robius’s earlier BNPL credit-report coverage. Its July prediction that BNPL data would necessarily move the numeric score was too broad. What is firmly established by the latest official announcement is expanded reporting. The score impact of any specific BNPL product should be checked against the Bureau’s current FAQs and the lender’s assessment, rather than inferred from a provider’s marketing.
There is a second distinction in the UAE BNPL regulatory framework: a brand’s legal permission to offer short-term credit, its reporting duties and the effect of its products on a customer’s score are separate matters. A regulated product is still a financial commitment, even when the checkout screen divides it into small payments.
A report explains more than a score
The Bureau’s individual Credit Report page currently lists the full report at AED84, including the score. The report contains the underlying credit contracts, payment history, income-utilisation information and court obligations. The score-only product is a different service; users should confirm its live price and purchase channel rather than assume every app or intermediary offers it on the same terms.
For a routine check, the number may be enough to notice movement. Before a mortgage, car finance application, tenancy screening or dispute, the full report is more actionable. It can show whether a loan appears twice, a closed account remains open, a settled amount is still marked outstanding or a service provider has submitted incorrect information.
The Bureau’s website and mobile app are the official consumer channels. The UAE government’s credit-report guidance also describes UAE PASS login and online payment. These are ways to obtain the report, not evidence that any particular bank will accept an application. Do not pay an unrelated intermediary for a supposedly special credit clearance without verifying what service it actually provides.
How to challenge wrong information
Etihad Credit Bureau offers a free Data Correction service for a Credit Report purchased within the preceding 30 days. It says that the information comes from banks, finance companies, telecom operators, utilities and other providers. The Bureau does not simply rewrite a disputed account on request; it refers the correction to the organisation that supplied the data.
Its published process is to review the report, select the incorrect entry, submit the correction request and supporting evidence, and await the provider’s response. The Bureau says the history should be updated within 10 working days, while also advising follow-up if there is no update. That is a stated service expectation, not a promise that every complex dispute will be settled by a fixed date.
If a data provider rejects the correction, the Bureau provides a separate dispute route through its contact centre. Keep a copy of the original report, the reference number, payment or closure evidence and the response. A genuine late payment is not a data error merely because it is inconvenient; a wrongly attributed account or incorrectly reported settlement may be.
Credit scores are moving beyond bank applications
The impact is wider than borrowing. The Bureau’s tenant-screening service in the UAE permits authorised property-side requesters to seek a prospective tenant’s score with consent through UAE PASS. That makes a score potentially relevant when a person rents a home, not just when they seek credit.
A person with a thin file may therefore face two different conversations. The Bureau can now provide a limited-history score to eligible newcomers, but a landlord may still prefer salary evidence, rent history or a guarantor. A bank can look at the score and still assess income, existing obligations, product criteria and its own risk appetite. The new score improves the information available; it does not replace individual judgement.
For new residents, the most practical approach remains to build accurate records from the start. Robius’s first-90-days financial guide covers the sequence of identity, banking and credit setup. The new model means an eligible person with a limited history may receive an initial score sooner, but there is no basis for promising a specific number or approval timeline.
The checks that matter next
For residents, the immediate questions are straightforward: Which of the two score models appears on your report? Are the listed facilities and payments accurate? Has a settled default been updated? Do your BNPL obligations appear? And is a prospective lender or landlord interpreting the score in the right context?
For the market, the next evidence should include how lenders actually use the new segments, whether the Bureau publishes updated score-grade bands, and whether its public explanations of BNPL reporting and numeric scoring remain consistent as more providers join. The October launch does not disclose bank-by-bank underwriting rules, and Robius has not tested individual lending outcomes.
The Robius conclusion: Score 3i makes the UAE credit file more inclusive and more explainable, but it also makes context more important. A 640 without its model label is incomplete information; six months without the repayment history is an incomplete recovery story; and a BNPL entry on a report is not proof of a particular score movement. Read the record before judging the number.
Sources
- Emirates News Agency, 29 October 2026: Etihad Credit Bureau’s official Score 3i launch, ranges, 36-month assessment, recovery conditions and BNPL reporting
- Etihad Credit Bureau: current individual Credit Score product and scoring-model information
- Etihad Credit Bureau: individual Credit Report contents and AED84 listed price
- Etihad Credit Bureau: personal Data Correction process, eligibility and follow-up route
- Etihad Credit Bureau: official FAQs for current credit-reporting and scoring questions
- UAE Government: how residents obtain an official credit report or score
- Khaleej Times, 29 October 2026: independent reporting on the launch and the conditional six-month recovery window
Checked 30 October 2026. Scoring ranges, assessment windows, recovery statements and reporting totals are attributed to Etihad Credit Bureau. No lender approval, personal score increase, app experience or BNPL scoring effect has been independently tested by Robius. Published product fees and procedures can change.
Robius.news | Dubai, UAE | 2026 | Built to be first. Built to be trusted.